

Cash App
by Block, Inc.
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 100.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
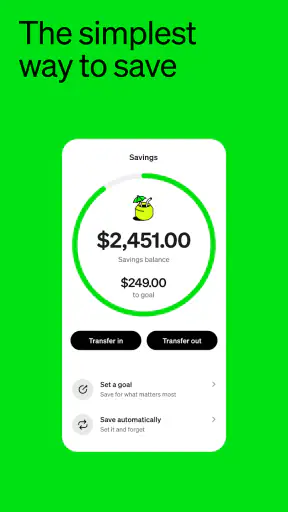
 Analysis by Getfullapps
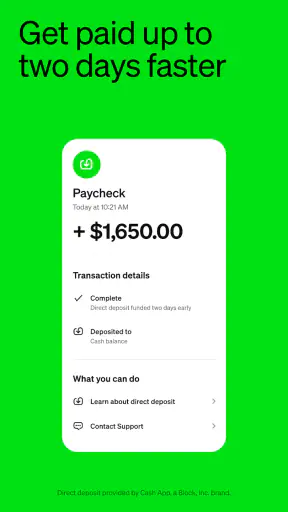
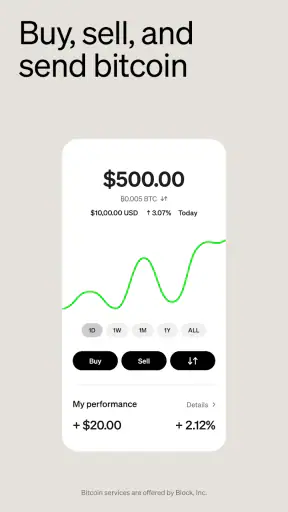
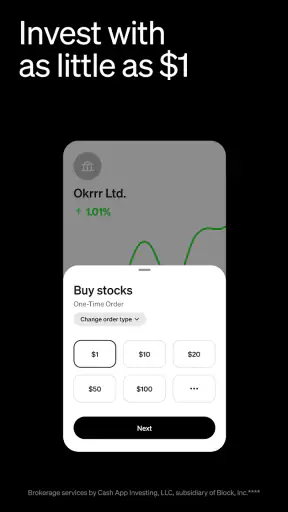
I came away from Cash App seeing it as a practical money hub rather than just a way to send a payment. It brings person-to-person transfers, banking tools, bitcoin, and investing into one mobile experience, which can be convenient when I want to handle a small financial task without moving between several apps. At the same time, that broad scope means the app deserves a little more attention than its simple name suggests.
Cash App is a free finance app from Block, Inc., rated for Everyone. It has been available since October 15, 2013, and its current version is 5.59.0 for devices running iOS or Android 10 and later. Its average rating is 4.7 from around 4.3 million ratings, with more than 100 million installs. Those figures tell me that this is not a niche wallet used only by a small group of enthusiasts; it is a familiar option for everyday money movement.
How Cash App feels when the network is part of the experience
The first thing I noticed is how strongly the app depends on a reliable connection. Sending money, checking a balance, moving through investing screens, or viewing bitcoin information all involve current financial information, so a weak signal can turn a quick task into a waiting exercise. I would not start an important transfer while moving through an area with unreliable reception and assume that a delayed screen means the action failed.
This matters because mobile payments often happen at exactly the wrong time: outside a shop, between errands, in a crowded venue, or while switching from Wi-Fi to cellular service. A loading screen is not merely inconvenient when money is involved. It can leave me unsure whether a payment was submitted, whether I should try again, or whether repeating the action could create a duplicate transaction.
My practical habit is to pause before retrying. I check the visible activity and balance information once the connection settles, then confirm what actually happened. That small step is more useful than tapping the same button repeatedly. It also highlights a broader point: Cash App can make a financial action feel immediate, but the surrounding network conditions still shape how confidently I can complete it.
The app is most comfortable when I have a stable connection and a moment to review the details. For a quick split between friends, that usually feels natural. For anything involving a larger amount, an investment decision, or bitcoin, I prefer to slow down and make sure the relevant screen has fully refreshed before confirming.
Everyday payments are where it makes the most sense
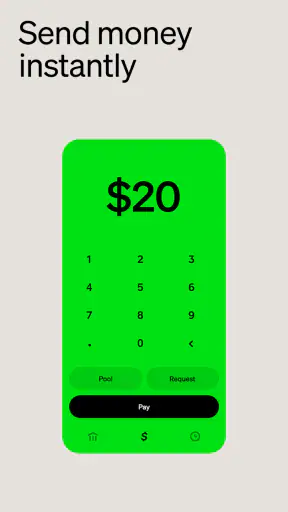
The clearest use case is sending money to someone I already know. Imagine a friend covering dinner while I am away from the table, or a roommate paying me back for a shared household purchase. Instead of handling cash or waiting for a bank transfer process, I can use the app from my phone and keep the exchange in one place.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
That convenience has a social advantage: it reduces the awkwardness of chasing a small repayment. I can send or request money while the expense is still fresh, rather than trying to remember it later. For recurring informal expenses, I find that immediacy more valuable than the app's extra financial features.
Still, I would be careful about treating every payment request as trustworthy. An easy interface does not remove the need to verify the recipient, the amount, and the reason for the transfer. My rule is simple: I check the identifying details before confirming, especially when responding to a request rather than starting a payment myself.
Cash App is less compelling if I mainly need formal household banking, detailed budgeting, or a broad set of account-management tools. A traditional bank app may be better for someone whose priority is a complete view of statements, scheduled payments, and established banking services. Cash App's strength is the short path from intention to action, not necessarily the deepest financial organization.
Using it while moving between places
Cash App is designed around the phone, so its value appears when I am away from a desk. I can think of it as a pocket tool for moments when carrying cash is inconvenient or when a payment comes up unexpectedly. That makes it useful for students, roommates, friends sharing travel costs, and people who regularly divide small expenses.
Mobile context also creates risks. A bright outdoor screen, hurried tapping, or a phone with little battery can make it harder to inspect a transaction carefully. I would avoid rushing through a payment while walking or standing in a noisy queue. The app may be quick to open, but financial details deserve the same attention I would give them on a larger screen.
The broad feature set can also work differently depending on where I am in my financial routine. Sending money is a short, occasional action. Investing and bitcoin require more deliberate attention because the decision is not finished when I tap into a market screen. I would not use the presence of those sections as a reason to trade impulsively; I see them as access points that still require independent judgment.
One useful workflow is separating urgent actions from exploratory ones. If I only need to repay a friend, I go directly to that task and avoid wandering through investment or bitcoin areas. If I want to review those options, I do it when I am stationary, connected, and able to read the information without distraction. This keeps the app from turning a simple payment moment into an unplanned financial decision.
What I do when a payment or screen does not behave normally
Connectivity problems are not the only source of friction. A payment can appear to take longer than expected, a balance may need time to update, or a screen may not show the information I expect immediately. My first response is not to assume that the money disappeared or that the transaction failed. I give the app time to reconnect, then inspect the activity and account information before taking another action.
This is especially important when a user has moved from Wi-Fi to mobile data. The phone may show a connection icon while the app is still waiting for a dependable exchange with its service. Closing and reopening the app can be a reasonable troubleshooting step, but I would do that only after noting what I already attempted and checking for a visible transaction record.
For a disputed or confusing situation, keeping a clear mental record helps: who the payment was for, the amount, when I initiated it, and what the app displayed afterward. I would also avoid sending a second payment simply because the first confirmation was slow. That is one of the most important practical lessons I took from using a mobile finance app: uncertainty is a reason to verify, not a reason to repeat.
Recovery is also about deciding when to stop. If the connection remains unstable, I would wait until I can use a more reliable network rather than repeatedly attempting a sensitive action. If the issue concerns an investment or bitcoin screen, I would be even more patient. A delayed quote or incomplete page is a poor basis for a financial decision.
This cautious approach may make Cash App feel less effortless than its quick-payment reputation suggests, but I consider that a healthy trade-off. The app can shorten the mechanics of moving money; it cannot eliminate the need to confirm what happened afterward.
Using the app without wasting mobile data
I do not think of Cash App as an app I need to keep open constantly. For ordinary payments, I open it when I have a specific task, complete the review, and leave it. That habit is sensible for both attention and data use: there is little benefit in repeatedly refreshing balances or market-related screens when I am not making a decision.
My data-conscious routine is straightforward. I use a dependable Wi-Fi connection for longer browsing, especially when I am reviewing several sections rather than sending one small payment. On cellular service, I keep the session focused, avoid unnecessary screen hopping, and wait for pages to finish loading before trying another action. I also avoid opening the app in a place where the signal is visibly unreliable if the task can wait.
This is not just about conserving a mobile allowance. A stable connection reduces the chance that I will misread a partial update or mistake a loading delay for a completed action. In a finance app, careful timing and careful reading are connected. Less unnecessary browsing can make the experience clearer, not merely lighter on data.
Notifications and phone settings also deserve common sense. I would review what appears on the lock screen and keep my device protected, because financial information can be sensitive even when the app itself is convenient. I would not hand an unlocked phone to someone just because the requested payment is small. Good mobile habits remain part of the Cash App experience.
Where it sits beside banks, wallets, and investment apps
Compared with a traditional bank app, Cash App feels more direct for informal payments and more compact for users who want several money-related functions in one place. A bank may feel stronger for established account services and formal financial administration. If my main need were managing a full banking relationship, I would compare those tools carefully instead of assuming a payment-focused app could replace everything.
Compared with a single-purpose digital wallet, Cash App offers a wider range of financial activities. That breadth is useful when I want to send money and later look at investing or bitcoin without installing a separate app. The trade-off is that the interface carries more responsibility: I need to know which area I am using and what kind of decision I am making.
Compared with a dedicated investing platform, the investment section may appeal to someone who values convenience over a specialized research environment. I would choose a more focused service if I wanted extensive analysis, advanced tools, or a workspace built primarily around portfolio decisions. Similarly, someone interested only in bitcoin may prefer a product designed specifically for that purpose.
That comparison helps define the right audience. Cash App is attractive to people who want a broad, approachable financial toolkit on a phone. It is less suitable for someone who wants one deeply specialized service, highly detailed financial planning, or a replacement for every function of a conventional bank.
Who should use it, and who should take a pass
I would recommend Cash App to a person who frequently sends or receives money from people they know and appreciates having banking, bitcoin, and investing options nearby. It is particularly practical for informal shared expenses, quick repayments, and users who prefer a mobile-first routine. The free price also lowers the barrier to trying it, although free access should not be confused with every possible financial action having no conditions.
I would be more cautious recommending it to someone who is uncomfortable checking recipient details, who often has an unreliable connection, or who wants a highly structured financial dashboard. A person who needs robust budgeting, formal banking administration, or specialized investment research may be happier with a bank or dedicated finance service. The app's convenience is real, but convenience is not the same as completeness.
I also would not recommend choosing it solely because it includes investing and bitcoin. Those sections make the app broader, not automatically better for every investor. Someone who is new to markets should treat them as areas requiring research and restraint, rather than as an invitation to act whenever a phone is in hand.
For families, the Everyone rating may make the app appear broadly approachable, but adults should still discuss safe payment habits with younger users. The financial consequences of a mistaken transfer are more important than the simplicity of the interface. I would focus on recipient verification, device security, and knowing how to respond when a transaction looks unfamiliar.
My connectivity verdict
After using Cash App as a mobile finance tool, I think its best quality is the way it brings common money actions close together. Sending money is the most immediately convincing part for me, while banking, bitcoin, and investing extend the app for users who want a wider financial routine in one place. Its large user base and strong average rating fit that practical appeal, but they do not remove the need to decide whether its scope matches my own needs.
The network-dependent nature of the experience is the main point I would explain to a friend. A reliable connection makes the app feel quick and straightforward; a weak one introduces uncertainty at exactly the moment when I want confirmation. I therefore use it with a pause-and-check mindset, particularly after a delayed payment or while switching networks.
My final recommendation is positive, with boundaries. Cash App is a good choice for convenient person-to-person payments and for users who like having several financial tools in a phone-based app. It is not my first choice for deep banking administration, advanced investing, or situations where connectivity is consistently poor. If I keep the app's strengths and limits in view, it becomes a useful everyday assistant rather than something I expect to handle every financial need.
In short, I would install it for quick, familiar payments and explore its broader features carefully. The most reliable experience comes from using a stable connection, checking every important detail, and treating delayed screens as a signal to verify rather than rush. For that kind of user, Cash App offers a convenient balance between everyday payments and broader money tools.
Pros
- User-friendly interface for easy navigation.
- Instant money transfers to friends and family.
- No fees for basic transactions.
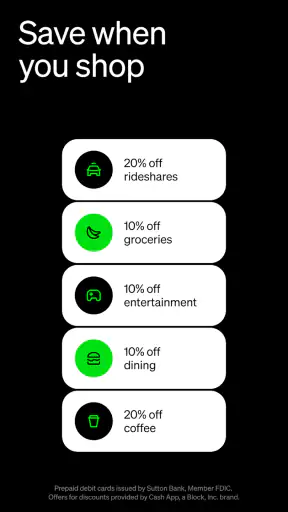
- Innovative Boost feature for discounts.
- Secure encryption for data protection.
Cons
- Limited customer support options available.
- Cash Card not accepted everywhere.
- Fees for instant bank transfers.
- Limited investment options compared to others.
- No joint accounts or multi-user access.
FAQs for Cash App
What is Cash App and how does it work?
Cash App is a mobile payment service that allows users to transfer money to one another using a mobile phone app. It provides a platform for sending and receiving money instantly, paying bills, and even buying stocks and Bitcoin. Users can link their bank account or use the Cash Card, a free debit card linked to their Cash App balance.
Is Cash App safe to use for transactions?
Yes, Cash App is generally considered safe. It uses encryption and fraud detection technology to secure users' data and transactions. However, users should always enable security features like PIN entry and two-factor authentication for added protection. It’s important to only send money to people you know and trust to avoid scams.
Are there any fees associated with using Cash App?
Cash App does not charge fees for standard transfers to and from your bank account, but there is a 1.5% fee for instant transfers. Sending and receiving money between friends and family is free. There may also be fees for certain services, such as ATM withdrawals from the Cash Card, unless you receive qualifying direct deposits.
Can I use Cash App internationally?
Cash App is currently available only in the United States and the United Kingdom. Users in these countries can send and receive money domestically. However, international transfers between the US and UK are also supported. For other countries, users will need to explore alternative payment apps that offer international services.
What should I do if I encounter a problem with Cash App?
If you experience any issues with Cash App, you can access the support options within the app. Navigate to your profile, select 'Support,' and follow the prompts to report a problem or access help articles. It’s also recommended to check the Cash App website for additional resources or contact their customer service for specific issues.

Cash App
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@squareup.com, visit https://cash.app, or review their https://cash.app/legal/us/en-us/privacy.










